KUALA LUMPUR: Sunway Healthcare Holdings Bhd is expected to deliver stronger earnings in the coming quarters, supported by rising bed occupancy, a more favourable patient case mix and the gradual filling of newly commissioned beds, according to RHB Research.
The research house maintained its “Buy” recommendation on the healthcare group with an unchanged target price of RM2.36, implying a potential upside of 12%, alongside an estimated dividend yield of about 1% for the financial year ending December 2027 (FY27).
RHB Research forecasts Sunway Healthcare's third-quarter 2026 (3Q26) revenue to rise 24% year-on-year (YoY) to RM734 million, while earnings before interest, taxes, depreciation and amortisation (EBITDA) are projected to increase 34% to RM178 million.
Core profit is estimated at RM86 million, up from the corresponding quarter last year, with higher patient volumes and greater treatment intensity expected to support the performance.
"We expect Sunway Healthcare to report sequentially stronger 3Q26 EBITDA and core profit of c. RM178 million and c. RM86 million on higher occupancy and an improved case mix, driving EBITDA margin improvements," the research house said in a note to clients today.
Patient admissions are projected to grow 17% year-on-year (y-o-y), while outpatient visits and daycare cases are expected to increase 15% and 22% respectively. Higher treatment intensity, supported by a more complex inpatient case mix, is also expected to contribute to revenue growth.
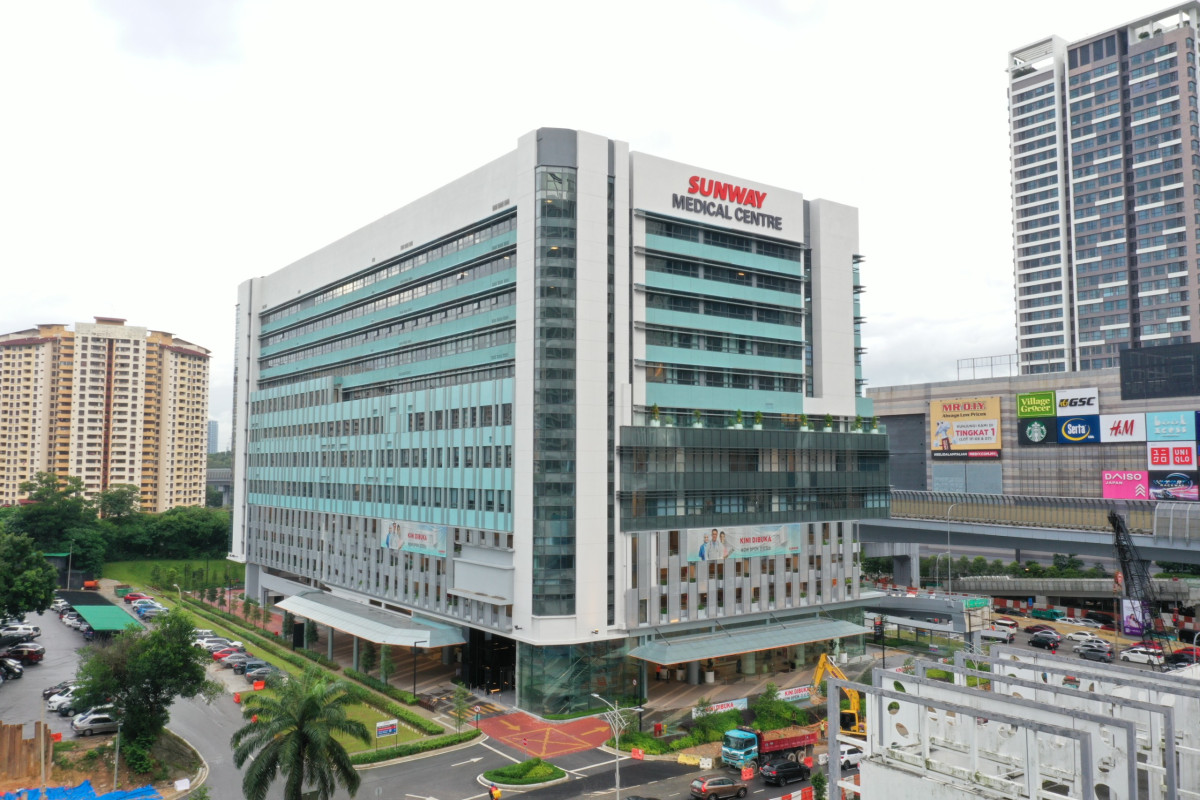
The expansion of Sunway Medical Centre Sunway City and Sunway Medical Centre Velocity is expected to support capacity growth. The former had licensed 108 of the 216 paediatric beds at Tower F by 3Q26, while the latter added 31 licensed beds in 2Q26.
RHB Research expects the EBITDA margin to improve to 24.2% from 23.8% in 2Q26, although it cautioned that the increase would be smaller than the previous quarter's improvement.
It also sees potential earnings upside from the recognition of investment tax allowances, which could lower the group's effective tax rate.
The brokerage marginally raised its FY26 to FY28 earnings forecasts by less than 1%, while keeping its target price unchanged.
"We still like Sunway Healthcare for its visible capacity runway which underpins a 29% compounded annual growth rate for FY25-28 core earnings per share," it said.
The group also has room to fund further expansion, with net gearing at 0.10 times as at 2Q26 and about 92% of proceeds of RM768 million from its initial public offering that have yet to be utilised.