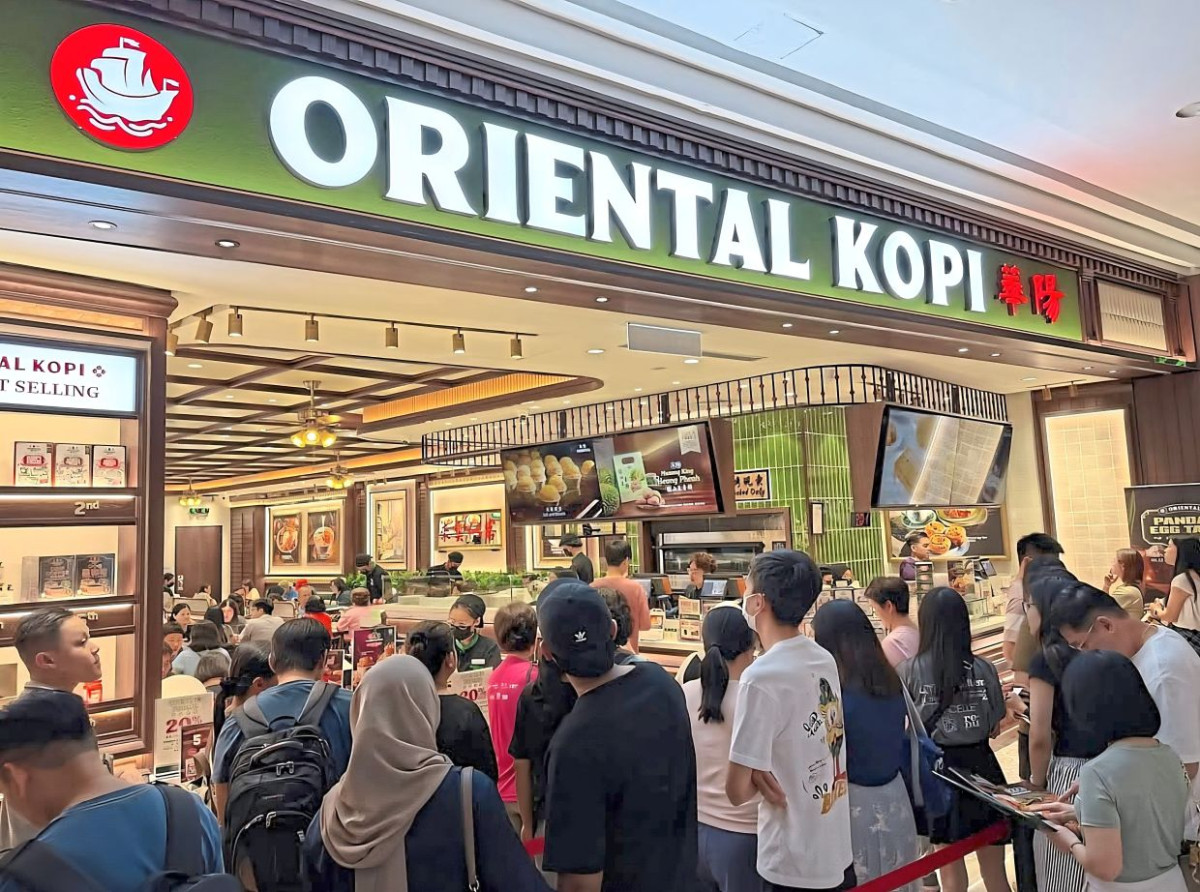
KUALA LUMPUR: Oriental Kopi Holdings Bhd is expected to sustain its earnings growth in the fourth quarter of its financial year ended Sept 30, 2026 (4QFY26), supported by contributions from newly opened outlets and stabilising gross profit margins, according to CGS International Research (CGSI Research).
The brokerage said the company’s October menu-language controversy had been resolved following the introduction of revised trilingual menus in November, noting: “We hosted Oriental Kopi Holdings' management and investors on 3 Nov 2026 to discuss its Oct 2026 menu language controversy.
"Management said that the matter has been resolved with its trilingual menus introduced in Nov 26 (at a reprinting cost of approximately RM150,000), with no material impact on footfall.”
The revised menus are currently being used at the group’s new Aman Central and Merdeka 118 outlets, with a rollout to its remaining locations expected by end-November.
CGSI Research said in a report to clients today that the three outlets opened over the 10 days preceding its report — Sunway 163, Aman Central and Merdeka 118 — had attracted long queues.
The research house said Oriental Kopi remained on track to operate 40 to 41 outlets in Malaysia by end-2026, compared with 34 as at July. Its medium-term plan to open eight to 10 outlets annually also appeared achievable, with six mall locations already secured.
As the group moves into second-tier shopping malls after securing most high-footfall locations, the research outfit expects rental costs to remain manageable. It noted that average outlet payback periods of 10 to 12 months continued to support returns.
Overseas expansion is also anticipated to provide another growth avenue, with the first Indonesian outlet targeted for end-November or early December, followed by Mauritius in the first quarter of 2027. Two Singapore outlets are planned for 2027, compared with three currently.
“We believe our FY26 core net profit forecast for Oriental Kopi of RM67.4mil is achievable, with a 4QFY9/26 core net profit of RM22mil (+50.0% year-on-year, +29.4% quarter-on-quarter), driven by new-store contributions and stabilising gross profit margins, amid steady raw material prices,” said CGSI Research.
The research house maintained its “Add” recommendation and target price of RM1.37, citing what it viewed as an undemanding valuation relative to the company’s historical average and the consumer sector.
It identified faster outlet expansion, stronger same-store sales growth and increased tourism-related demand as potential share price catalysts. Key downside risks include intense food and beverage competition, higher labour costs and pre-opening expenses from a heavier outlet-opening schedule in 1QFY27.