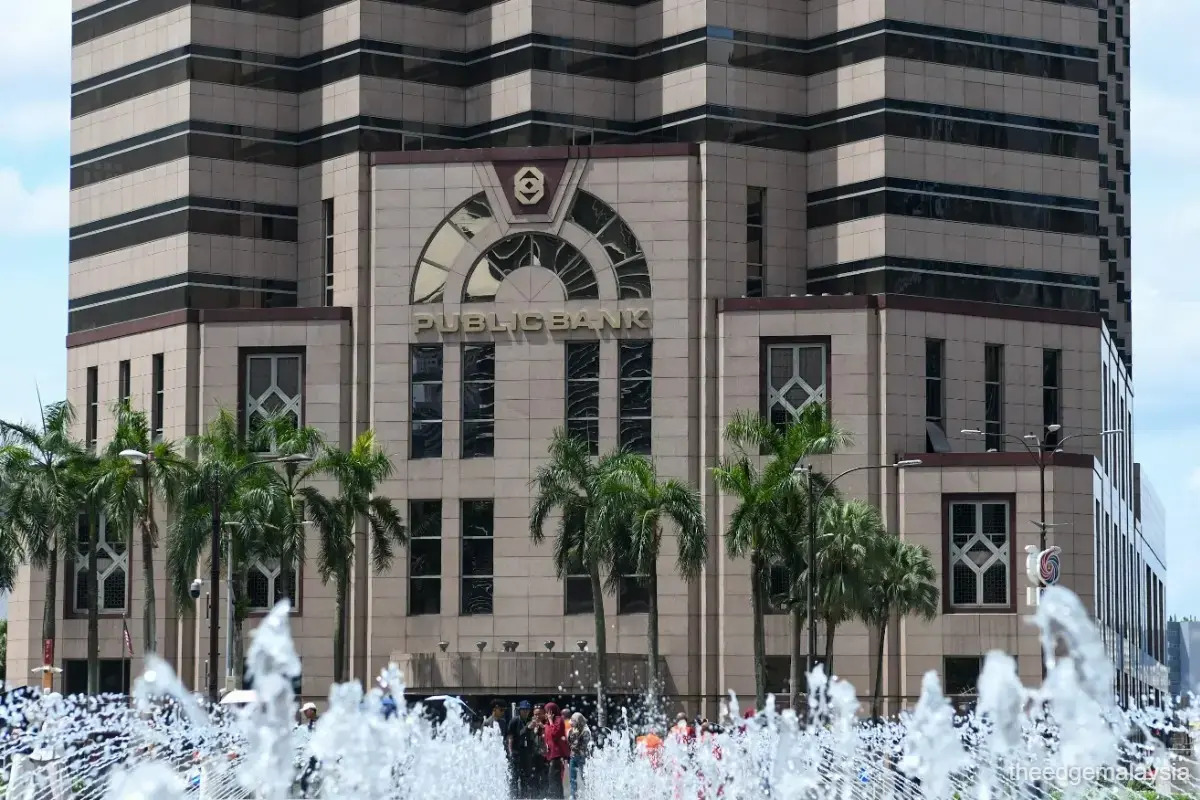
KUALA LUMPUR: PBBANK could see improved profitability in 2027 as management shifts its focus towards protecting margins and strengthening fee-based income, while its resilient asset quality and attractive dividend yield continue to support its investment appeal, according to analysts.
AmBank Research expects the banking group to benefit from normalising credit costs and sustained growth in non-interest income (NOII), despite near-term pressure from net interest margin (NIM) compression.
The brokerage maintained its "Buy" recommendation on Public Bank but lowered its target price to RM5.40 from RM5.60, based on 1.57 times its financial year 2027 price-to-book value (P/B), implying a potential upside of 16%.
It said the recent share price correction had restored some value to the stock, with its dividend yield of approximately 6% making the risk-reward proposition more attractive.
"We expect a brighter 2027 as profitability takes precedence over growth, anchored by resilient NOII and normalising NCC," AmBank Research said in a note to clients today, referring to non-interest income and net credit costs.
CGS International (CGSI) Research, meanwhile, reiterated its "Add" call on Public Bank, retaining its dividend discount model-based target price of RM6.55.
Its positive investment view is premised on the bank's efforts to grow fee income, potential capital management initiatives and an expected improvement in return on equity (ROE) over the 2026-2028 forecast period.
The differing target prices reflect the research houses' respective valuation approaches, although both highlighted fee income growth as an important earnings support.
Public Bank's third-quarter 2026 net profit fell 4% year-on-year (y-o-y) and 3% quarter-on-quarter to RM1.8 billion, bringing its nine-month net profit to RM5.4 billion, largely unchanged from a year earlier.
AmBank Research said the nine-month performance was below its expectations at 71% of its full-year forecast, although it was broadly in line with the 75% consensus estimate, mainly due to higher-than-expected loan loss allowances.
CGSI Research said the bank's nine-month core net profit accounted for 72.3% of its full-year forecast and Bloomberg consensus estimate, keeping the performance within expectations.
Both research houses highlighted fee income as a bright spot. CGSI Research noted that Public Bank's fee income increased 10.3% y-o-y in the nine months to September, driven mainly by a 26.5% rise in asset management income.
The growth helped lift non-interest income by 7% y-o-y, offsetting a sharp increase in loan loss provisioning, which rose 251% from a relatively low base in the corresponding period last year.
AmBank Research also noted that quarterly fee income had exceeded RM600 million, compared with an average of approximately RM560 million in 2025.
It said the relatively sticky nature of fee income should provide greater resilience to the bank's non-interest income going forward.
However, margin pressure and higher provisioning remain near-term challenges. Public Bank's NIM contracted by five basis points quarter-on-quarter in the third quarter, while management revised its full-year NIM decline guidance to nine to 10 basis points from a previous mid-single-digit expectation.
Management also lowered its ROE guidance to 12% from 12% to 13%, while raising its non-credit cost (NCC) guidance to 10 basis points from its earlier single-digit expectation.
Nevertheless, AmBank Research said underlying asset quality remained sound, with the gross impaired loan ratio holding at 0.55%, loan loss coverage at a healthy 135% and loans overdue by more than a month improving to 1.5%.
"Taken together, these suggest little evidence of emerging credit stress," it said.
CGSI Research also noted that Public Bank's mark-to-market losses on fair value through profit or loss securities amounted to only RM11.6 million in the third quarter, below its RM39.7 million estimate, with no material impact on earnings.
Looking ahead, CGSI Research expects capital management initiatives to potentially lift the dividend payout ratio above 70% in the financial years ending December 2026 to 2028 (FY26-28), while forecasting ROE to improve from 12.3% in FY25 to 12.8% in FY28.
AmBank Research, however, trimmed its FY26-28 earnings forecasts by 3% to 5% to reflect the weaker margin outlook and higher credit costs, while CGSI Research maintained its earnings forecasts.
Meanwhile, the lender's shares came under pressure on Tuesday after the bank lowered its return on equity (ROE) guidance and signalled a steeper contraction in net interest margin (NIM), raising concerns over its near-term profitability.
The bank's ROE is now expected to be closer to 12% for the full year, compared with its previous guidance range of 12% to 13%, while NIM could decline by nine to 10 basis points amid heightened competition for deposits and a more challenging funding environment.
CIMB Securities said the revised guidance did not necessarily point to a weakening of the bank's underlying business franchise.
"We continue to view these revisions as reflecting a more challenging funding environment rather than a deterioration in underlying franchise strength," it said.
Public Bank fell as much as 20 sen, or 4%, to RM4.70 on Tuesday, making it the biggest decliner among banking stocks and weighing on the .
Despite an early morning charge that mirrored Wall Street's overnight gains, the Bursa Malaysia then fell 18.27 points to hover below the psychological 1,600 threshold at 1,598.31 11:13AM, becoming the notable exception to major regional bourses that all advanced.
Malaysian banking stocks have faced selling pressure in recent months as bond yields climbed, potentially resulting in mark-to-market losses on banks' existing bond holdings as prices move inversely to yields.
For the January-September 2026 period, Public Bank recorded an ROE of 11.7%, while its NIM contracted by nine basis points, a sharper decline than the mid-single-digit reduction previously anticipated. The bank, however, maintained its other guidance, including its loan growth outlook.
Despite the recent weakness, Public Bank's share price remained up nearly 9% year-to-date. Of the 20 analysts tracked by Bloomberg, 15 had "Buy" recommendations, while the remaining five maintained "Hold" calls. The average target price stood at RM5.47.
Hong Leong Investment Bank maintained its "Buy" recommendation, expecting the bank to sustain loan growth momentum on the back of resilient domestic demand and continued expansion in the small and medium enterprise segment.