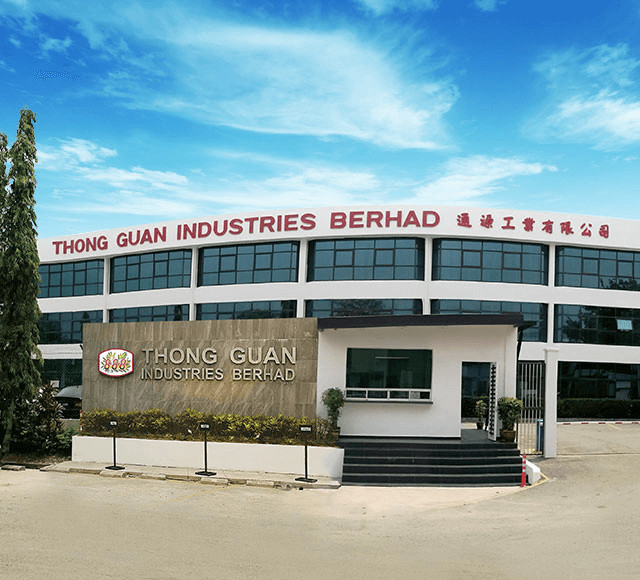
KUALA LUMPUR: Thong Guan Industries Bhd expects its operating environment to remain challenging for the rest of 2026 due to ongoing geopolitical uncertainties, persistent global economic volatility, and shifting trade and monetary policies across major economies.
In a Bursa Malaysia filing on Wednesday, the plastic packaging manufacturer noted that demand for plastic packaging products remains uncertain, depending on geopolitical developments, market conditions, and customers' inventory replenishment patterns.
For the third quarter ended September 30, 2026 (3Q26), Thong Guan's net profit nearly quadrupled year-on-year (y-o-y) to RM49.81 million, compared with RM13.44 million in 3Q25. Earnings per share rose to 12.66 sen from 3.36 sen previously.
Quarterly revenue climbed 20.6% y-o-y to RM358.41 million from RM297.28 million, while profit before tax (PBT) jumped 287.3% to RM66.39 million from RM17.14 million. The stronger performance was primarily driven by its plastic packaging division, which posted a 20.4% y-o-y revenue increase to RM309.72 million and a more than fivefold surge in PBT to RM58.60 million on higher average selling prices (ASP), stronger sales volumes for stretch film and garbage bags, and the utilisation of lower-cost resin inventories.
The property development segment also contributed RM7.98 million in revenue and RM1.89 million in PBT during the quarter.
On a quarter-on-quarter (q-o-q) basis, revenue dipped 6.9% from RM384.79 million in 2Q26, while net profit declined 16.5% from RM59.7 million. The sequential softening was mainly due to lower sales volumes of stretch films, industrial bags, and PVC food wrap products.
For the cumulative nine-month period (9M26), net profit jumped 171.7% y-o-y to RM130.24 million from RM47.94 million, while revenue grew 16.1% to RM1.06 billion from RM913.25 million.
Alongside the results, the board proposed a single-tier interim dividend of two sen per ordinary share for 3Q26, bringing total dividends to seven sen per share for the fiscal year ending December 2026.
While recent performance benefited from lower-cost resin inventories, the group cautioned that this advantage is expected to moderate as stocks are replenished at prevailing market prices, alongside fluctuations in resin costs and shipping lead times.
To navigate these headwinds, Thong Guan will closely monitor resin price movements and shipping conditions while maintaining prudent inventory management, operational efficiency, and cost discipline.
Meanwhile, its food, beverages, and other consumable products division is expected to provide steady earnings support, while the property development segment is anticipated to contribute increasingly to overall performance. Barring unforeseen circumstances, the group remains well-positioned to sustain its growth momentum.