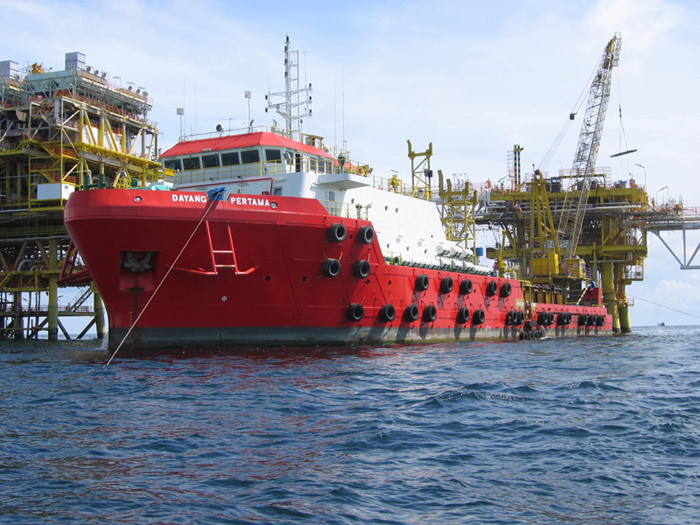
KUALA LUMPUR: Dayang Enterprise Holdings Bhd expects offshore oil and gas activities to remain subdued in the near term as the industry enters the monsoon season, with soft activity levels projected to persist through the first half of 2027 amid market uncertainties and measured spending by oil majors.
While management remains cautiously optimistic about the sector’s longer-term prospects, any recovery is anticipated to be gradual, with potential improvement only towards the second half of 2027 depending on market conditions and contract awards.
Despite the softer operating climate, Dayang’s earnings visibility remains anchored by an existing contract order book of approximately RM4.66 billion, alongside a newly incorporated Brunei joint venture, Petrokon Dayang Corporation Sdn Bhd, to pursue regional opportunities.
For the third quarter ended Sept 30, 2026 (3Q26), Dayang’s net profit fell 52.5% year-on-year (y-o-y) to RM38.15 million from RM80.29 million in 3Q25, with basic earnings per share easing to 3.29 sen from 6.93 sen. Pre-tax profit dropped 62.2% y-o-y to RM51.08 million from RM135.10 million.
Quarterly revenue declined 46.0% y-o-y to RM165.25 million from RM305.77 million. The contraction was primarily due to a slower order book conversion rate in the topside maintenance segment, where external revenue fell 51.8% y-o-y to RM68.7 million on fewer work orders and call-outs from oil majors, compounded by a lower vessel utilisation rate of 58% compared with 80% a year earlier.
Reduced third-party vessel chartering and catering income, alongside the absence of a RM10.24 million net gain on impairment of financial instruments recognised in 3Q25, further weighed on earnings.
No dividend was declared for the quarter under review, following an earlier first interim single-tier tax-exempt dividend of 7 sen per share for FY2026 paid in June.
On a quarter-on-quarter (q-o-q) basis, however, net profit rose 16.2% from RM32.84 million in 2Q26, while pre-tax profit increased 9.1% from RM46.83 million.
Sequential revenue edged up 2.5% from RM161.18 million, supported by higher topside maintenance work orders executed during the quarter, stable vessel utilisation, and higher interest income from surplus fund placements.
For the nine months ended Sept 30, 2026 (9M26), cumulative net profit decreased 45.3% y-o-y to RM92.51 million from RM169.24 million, while nine-month revenue fell 36.9% y-o-y to RM458.78 million from RM726.94 million.